 Hong Kong incorporation fee & Aspire
 cashback.


Table of Contents
Goods and services tax in Singapore is a 9% consumption tax charged on most goods, services and imports, collected by GST-registered businesses on behalf of the Inland Revenue Authority of Singapore (IRAS).
Registration becomes compulsory once your taxable turnover exceeds S$1 million, though smaller businesses may still register voluntarily. This guide covers current rates, registration rules, exemptions, filing deadlines and penalties.
Key Takeaways
- GST is currently charged at 9%, effective since 1 January 2024(1) — the second step of a two-stage increase, with no further rate change confirmed as of August 2026.
- Compulsory registration applies once taxable turnover exceeds S$1 million(2) (retrospective) or is reasonably expected to exceed it in the next 12 months (prospective).
- GST registration is completed online via myTax Portal using Corppass — there is no separate paper GST F1 process for standard applications.
- Businesses can apply for exemption from registration if zero-rated supplies exceed 90%(3) of total taxable supplies and they would be in a net refundable position.
- Late payment triggers a 5% penalty, plus an additional 2% per month (capped at 50% of the unpaid tax) if the amount remains unpaid 60 days after the due date(4) .
What is the Goods and Services Tax (GST) in Singapore?
Goods and Services Tax in Singapore is a broad-based consumption tax charged on the supply of most goods and services in Singapore and on the import of goods, currently at a rate of 9%, and administered by the Inland Revenue Authority of Singapore (IRAS).
Better known as Value Added Tax or VAT in some regions, GST is an indirect tax, meaning that it is collected and then remitted back to the government by a GST-registered business acting as an intermediary.
As a GST-registered business owner, you must understand and manage input and output taxes effectively as part of financial and compliance responsibilities.
When purchasing supplies for business operations, the incurred tax is known as input tax. Subsequently, when customers purchase goods or services, the tax collected from them is referred to as output tax.
Upon filing the GST return, businesses must reconcile the output and input taxes. If the output tax exceeds the input tax, a payment is required to cover the difference, whereas if the input tax surpasses the output tax, a refund may be obtained.
Businesses need to ensure compliance with GST regulations and fulfill the role of intermediaries in collecting and remitting GST on behalf of the government. In Singapore, the rate of GST is currently 9%, according to the Inland Revenue Authority of Singapore (IRAS).

For example
If you charge a customer S$500 for a service, you add 9% GST (S$45), so the customer pays S$545 in total. You keep the original S$500 and remit the S$45 collected to IRAS when you file your GST return.
How GST is calculated
GST is worked out by applying the applicable rate to the value of a taxable supply. For standard-rated supplies, GST is charged at 9% of the selling price. For zero-rated supplies, GST is charged at 0%, so no GST is added to the price. For exempt supplies, no GST is charged at all, and the business cannot recover any GST it paid on related purchases.
For example, if you charge a customer S$500 for a standard-rated service, you add 9% GST (S$45), so the customer pays S$545 in total. You keep the original S$500 and remit the S$45 collected to IRAS when you file your GST return.
To work out how much GST your business actually owes IRAS for an accounting period, use this formula:
If your output tax (the GST you collected from customers) is higher than your input tax (the GST you paid on business purchases), you pay the difference to IRAS. If your input tax is higher, you are entitled to a refund of the difference.
Output Tax vs Input Tax
The table below summarises the difference between the two.
| Output Tax | Input Tax | |
| What it is | GST you collect from customers when you sell taxable goods or services | GST you pay to your suppliers when you buy goods or services for your business |
| When it applies | When you make a standard-rated sale | When you make a business purchase from a GST-registered supplier |
| Effect on your GST bill | Increases the amount you owe IRAS | Reduces the amount you owe IRAS |
| Refund | Not refundable, it is money collected on IRAS’s behalf | Refundable if your input tax exceeds your output tax for the period |
The requirement for GST registration in Singapore
There are two types of GST registration in Singapore: voluntary registration and compulsory registration.
Compulsory registration
This applies to businesses with annual taxable turnover exceeding SG$1 mil in the past 12 months or expected to exceed within the next 12 months.
Once your company’s taxable turnover reaches more than S$1 million, you are given a time limit of 30 days to file the GST application with IRAS. Any failure to miss this deadline would result in penalties.
Voluntary registration
This is available for businesses with turnover lower than S$1 million. In some cases, voluntary registration can be beneficial for new or small businesses as it allows them to claim input tax refunds.
Voluntary GST registrants must remain registered for at least two years before applying to deregister. Company directors, sole-proprietors, partners and preparers of GST returns are also required to complete IRAS’s e-Learning course on GST before a voluntary registration is approved.
How to register for GST in Singapore
Once you have decided to register for GST, the steps are fairly straightforward.
- Online application: Apply for GST registration online by using your Corppass account to log into myTax Portal.
- Via local agent: Foreign entities who did not register their businesses in Singapore must appoint a local agent to take care of GST matters on their behalf.
Make sure you have all the necessary documents ready before starting the application, which may include:
- Your company’s business profile and details
- Financial statements for the past 12 months
- Expected taxable turnover for the next 12 months
- Other supporting documents required by the IRAS
After registering for GST, businesses are required to file their returns on a regular basis. Late or incorrect filing may result in penalties and fees, so it is important to stay compliant with GST regulations.
Types of supplies exempted from GST in Singapore
You would have to pay GST if you render any goods or services that are labeled as standard-rated supply.
Most goods and services in Singapore are standard-rated, but several categories receive different GST treatment. The table below summarises the main types of supply:
| Supply Type | GST Treatment | Examples |
| Standard-rated | 9% | Most goods and services sold in Singapore |
| Zero-rated | 0% | Exported goods; international services meeting Section 21 of the GST Act |
| Exempt | No GST charged | Sale and lease of residential property; most financial services; investment precious metals (IPM); digital payment token transactions |
| Out-of-scope | Not subject to GST | Goods sold and delivered entirely overseas; sales within a Free Trade Zone/Zero GST Warehouse; private non-business transactions |
GST and Service Charge in Singapore
In the hotel and food & beverage (F&B) industry, businesses often add a service charge, typically 10%, on top of the bill. IRAS treats this service charge as part of the total price for goods and services provided, so GST must be calculated on the total price payable, i.e. the base price plus the service charge, not on the base price alone.
For example, if a meal costs S$100 and a 10% service charge (S$10) applies, the subtotal is S$110. GST at 9% is then charged on that S$110, adding S$9.90, for a final bill of S$119.90.
IRAS does not regulate whether a business must impose a service charge, or how the collected amount is used internally, that is a commercial decision between the business and its staff.
Hotels and F&B establishments that impose a genuine service charge are also given an exception from the general rule requiring GST-inclusive price display: they may show “++” (GST and service charge exclusive) prices, provided they display a prominent statement that prices shown are subject to GST and service charge.
This exception does not apply to businesses that impose only a nominal service charge to avoid GST-inclusive pricing, or that do not impose a service charge at all.
Exemption from GST registration in Singapore
Fortunately, you can seek an exemption from the requirement to register for GST if:
- Zero-rated supplies over total taxable supplies exceed 90%
- The company would be in a net refundable position had it been GST-registered
As soon as you get the seal of approval from IRAS, you are not obliged to GST registration and avoid the process of filing it several times a year.
You can also apply for exemption of GST registration if you qualify for registration under a retrospective basis but you expect to see a significant decrease in sales volume that could result in taxable turnover falling below S1 million in the next 12 months.
If you no longer meet these exemption conditions and your annual taxable turnover exceeds S$1 million, you must notify IRAS within 30 days so your GST registration can be processed.
Goods and Services Tax deregistration in Singapore
You must cancel the GST registration under any of the following scenarios:
- You stopped selling taxable goods or services, and do not intend to revert in the future.
- Your business has ceased
- The entire business is transferred to a new owner
- There has been a change in the structure of your company (e.g., from a general partnership to a limited liability partnership, or from a sole proprietorship to a private limited company). The next step is to determine whether GST registration is required for the new business entity.
You can also apply for GST deregistration voluntarily if your taxable turnover in the next 12 months is expected to decrease below S$1 million. In such a case, you will be asked to provide supporting documents as proof.
In addition, applying for cancellation of voluntary GST registration would require a business to remain registered for at least 2 years before deregistration.
Should you wish to file a petition for deregistration, you first need to lodge an application form attached with other relevant documents within 30 days from the date your company halts the collection of GST.
The consequences of failing to file GST in Singapore
Both GST return and payment fall due one month following the end of your accounting period.
If you miss the deadline for making a tax payment, your business would incur a penalty of 5% for the first month of late payment.
Unpaid taxes may be subject to an additional 2% penalty per month, not to exceed 50% of the unpaid amount, if they remain unpaid 60 days after the imposition of the 5% late payment penalty.
If IRAS sees that you are neglecting the duty to file the return, they would notify you of your violation by sending a “Notice of Assessment” with their estimated tax plus a penalty of 5% percent.
A further penalty of $200 would be imposed immediately for the first month of late filing and any subsequent months with outstanding GST returns, which would be accumulated until reaching the $10,000 cap.
Some incentives for Goods and Services in Singapore
Under IRAS, an owner of a company regardless of scope is offered a wide range of GST Incentives Schemes, the purpose of which is to help businesses ease the trouble of excessive red tape and drive growth for Singapore’s overall economy.
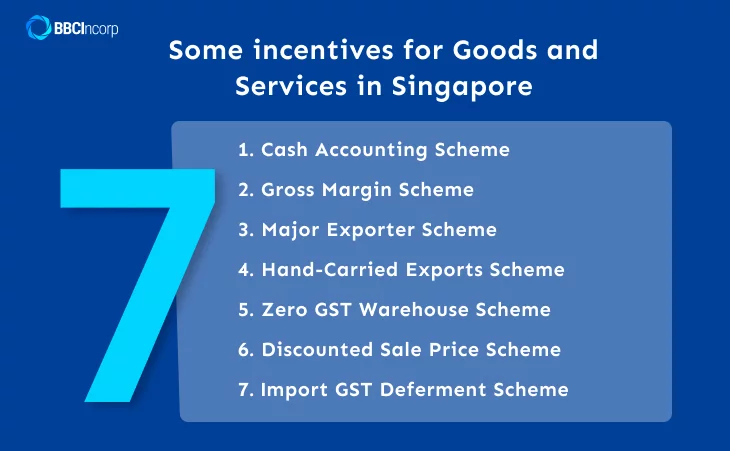
- Cash Accounting Scheme: A small business whose annual turnover is less than S$1 million can account for output tax upon receipt of the payment.
- Gross Margin Scheme: For second-hand businesses with no GST input, GST is assessed based on the gross margin instead of the total value of the goods and/or services you render.
- Major Exporter Scheme: Import – Export businesses handling a vast amount of zero-rated goods are allowed to suspend their GST.
- Hand-Carried Exports Scheme: goods that are hand-carried out of Singapore by overseas customers via Changi International Airport can be exempted from GST.
- Zero GST Warehouse Scheme: under certain conditions, a business owner can store their imported non-dutiable goods for as long as he/she pleases in a licensed premise while enjoying GST suspension.
- Discounted Sale Price Scheme: Second-hand or used vehicles can be charged 50% of the selling price for GST purposes.
- Import GST Deferment Scheme: For approved businesses, the GST payment levied on the imported goods can be deferred until the due date of filing due of filing GST returns instead of paying at the time of importing goods.
Conclusion
Understanding GST in Singapore at the 9% standard rate, including who must register, which supplies qualify for zero-rating or exemption, and how penalties work, helps you stay compliant and avoid unnecessary costs. Whether GST registration is compulsory or voluntary for your business, keeping accurate records of input and output tax is essential for smooth filing.
If you need help with the GST registration process or setting up your business in Singapore, chat with us and our team will guide you through the requirements.
References:
- Inland Revenue Authority of Singapore – GST rate change for consumers: https://www.iras.gov.sg/taxes/goods-services-tax-(gst)/gst-rate-change/gst-rate-change-for-consumers1
- Inland Revenue Authority of Singapore – Do I need to register for GST: https://www.iras.gov.sg/taxes/goods-services-tax-(gst)/gst-registration-deregistration/do-i-need-to-register-for-gst
- Inland Revenue Authority of Singapore – Applying for exemption from GST registration: https://www.iras.gov.sg/taxes/goods-services-tax-(gst)/gst-registration-deregistration/applying-for-exemption-from-gst-registration
- Inland Revenue Authority of Singapore – Late payment or non-payment of GST: https://www.iras.gov.sg/taxes/goods-services-tax-(gst)/gst-payments-refunds/late-payment-or-non-payment-of-gst
Frequently Asked Questions
What is the current GST rate in Singapore?
The current GST rate in Singapore is 9%, effective since 1 January 2024. As of August 2026, IRAS has not announced any further rate change.
Do I need to register for GST if my turnover is below S$1 million?
No, registration is not compulsory below the S$1 million threshold, but you may register voluntarily if you meet IRAS’s conditions. Voluntary registrants must remain GST-registered for at least two years before applying to deregister.
How do I apply for GST registration?
You apply online through myTax Portal (mytax.iras.gov.sg) using your Corppass login. Foreign entities without a Singapore business presence must appoint a local agent to handle GST matters on their behalf.
What happens if I pay GST late?
IRAS imposes a 5% late payment penalty on the outstanding tax. If the amount remains unpaid 60 days after that penalty, an additional 2% per month applies, capped at 50% of the unpaid tax.
Can I be exempted from GST registration even if I exceed S$1 million in turnover?
Yes, if your zero-rated supplies exceed 90% of total taxable supplies and you would be in a net refundable position if registered. You must notify IRAS within 30 days if you stop qualifying for the exemption.
Is service charge at a restaurant or hotel subject to GST?
Yes. IRAS treats service charge as part of the total price for goods and services provided, so GST is calculated on the base price plus the service charge, not on the base price alone. A S$100 bill with a 10% service charge becomes a S$119.90 total once 9% GST is applied.
Disclaimer: While BBCIncorp strives to make the information on this website as timely and accurate as possible, the information itself is for reference purposes only. You should not substitute the information provided in this article for competent legal advice. Feel free to contact BBCIncorp’s customer services for advice on your specific cases.
Industry News & Insights
Get helpful tips and info from our newsletter!
Stay in the know and be empowered with our strategic how-tos, resources, and guidelines.


