 Hong Kong incorporation fee & Aspire
 cashback.


Table of Contents
What is provisional tax in Hong Kong? It is an advance tax charge generally calculated by reference to the preceding year’s assessable income, profits, or assessable value. The Inland Revenue Department (IRD) uses this system to ensure a steady flow of tax revenue while spreading taxpayers’ obligations more evenly.
However, many individuals and businesses misunderstand how provisional tax works, leading to overpayment or even penalties.
If you’ve ever wondered why you’re paying tax before earning income, here is the article for you. Let’s explore how provisional tax Hong Kong is calculated and how the holdover mechanism reduces or defers payment when your income declines.
Key Takeaways
- Provisional tax applies to three tax categories: Salaries Tax, Profits Tax, and Property Tax.
- The calculation normally uses prior-year figures: Tax paid is later credited against the final liability and the next provisional assessment.
- Salaries Tax uses the lower calculation: IRD compares progressive rates with the applicable standard rates.
- Eligible businesses may use two-tiered Profits Tax rates: Different rates apply to corporations and unincorporated businesses.
- Holdover applications have strict conditions: Taxpayers must establish an accepted ground and submit Form IR1121 within the prescribed deadline.
What is provisional tax and why is it charged?
Paying tax before earning income may sound unusual, but provisional tax is a key part of Hong Kong’s tax system.
What is provisional tax Hong Kong
Provisional tax in Hong Kong is an advance payment of income tax based on your previous year’s taxable income. Instead of waiting until the end of the next assessment year, the Inland Revenue Department (IRD) estimates your upcoming income and collects tax in advance to align with your expected earnings.
This system applies to three major tax categories:
- Salaries tax for individuals
- Profits tax for businesses
- Property tax for landlords
The provisional tax is later adjusted against your final tax assessment once the actual income is reported. If you have overpaid, the excess will be refunded or used to offset the next year’s provisional tax.
Simply put, the final assessment reflects your actual income for the year, while provisional tax represents a forecast based on past figures. The two payments are interrelated but serve different timing purposes.
Purpose of charging provisional tax in Hong Kong
The government’s rationale for charging provisional tax lies in maintaining stable cash flow and timely tax collection. Hong Kong operates under a pay-later income tax system, where taxes are typically settled after the end of the financial year.
Without provisional tax, large volumes of payments would arrive at once, creating pressure on both taxpayers and the IRD. By collecting tax in advance, the government secures a steady flow of revenue to fund essential public services such as healthcare, education, and infrastructure throughout the year.
From a taxpayer’s perspective, the provisional tax system also helps distribute the payment burden more evenly. Instead of settling the entire liability at once, individuals and companies pay in two installments, easing the impact on their finances.
According to the IRD, the first installment usually equals 75 percent of the provisional tax, with the remaining 25 percent due later in the year.
In short, provisional tax HK plays a vital role in keeping Hong Kong’s income tax system efficient and predictable. At the same time, it allows adjustments through the final assessment once the actual income is confirmed.
How to calculate provisional tax in Hong Kong
As stated, calculating provisional tax in Hong Kong involves estimating the upcoming year’s tax liability based on the previous year’s assessable income. Here’s how to calculate provisional tax so you can manage payments efficiently and avoid overpayment or cash flow issues.
Standard calculation method
Provisional tax is computed using assessable income from the preceding year as a reference. The IRD assumes income for the following year remains similar unless there is valid evidence of change.
Provisional tax under salaries tax
Under salaries tax, provisional tax is based on net chargeable income after deductions and allowances, using the progressive rates below:
| Net chargeable income (HK$) | Tax rate (%) |
| First 50,000 | 2 |
| Next 50,000 (50,001–100,000) | 6 |
| Next 50,000 (100,001–150,000) | 10 |
| Next 50,000 (150,001–200,000) | 14 |
| Remainder (Above 200,000) | 17 |
Alternatively, Salaries Tax is calculated at the applicable standard rates on net income before personal allowances. From the year of assessment 2024/25, the standard rates are 15% on the first HK$5 million of net income and 16% on the remainder.
The IRD compares this amount with the tax calculated at progressive rates on net chargeable income, and the lower amount applies(1).

For example:
Suppose a taxpayer has net income of HK$1,200,000 and net chargeable income of HK$1,000,000 after deductions and allowances. Tax calculated at progressive rates would be HK$152,000, while tax calculated at the applicable standard rate would be HK$180,000. The tax payable before any applicable tax reduction would therefore be HK$152,000, as this is the lower amount.
Provisional tax under profits tax
Provisional Profits Tax is generally calculated using the assessable profits of the preceding year. For corporations eligible for the two-tiered Profits Tax rates:
- The first HK$2 million of assessable profits is taxed at 8.25%
- The remaining assessable profits are taxed at 16.5%
For eligible unincorporated businesses, the corresponding rates are 7.5% and 15%. Businesses that do not qualify for the two-tiered regime are generally taxed at the normal rates of 16.5% for corporations or 15% for unincorporated businesses.
For example, an eligible corporation with HK$1 million in assessable profits would pay HK$82,500 in provisional Profits Tax before any applicable tax reduction.
When the final assessment is issued, the provisional tax paid is credited against the final liability. Any excess is refunded or applied to the next provisional assessment.
Special considerations and exceptions
If expected net chargeable income, assessable profits, or assessable value is less than 90% of the relevant assessed amount, or another statutory ground applies, the taxpayer may apply for a holdover of provisional tax. The application must be submitted within the prescribed deadline with supporting calculations and documents.
For first-time Salaries Tax taxpayers, the IRD may estimate income using information provided by the taxpayer and employer. The actual income is later used to determine the final tax liability and the following year’s provisional tax.
Taxpayers should review their demand note promptly and apply for a holdover if the provisional assessment no longer reflects their expected tax position.
When and how is provisional tax paid?
Provisional tax HK follows a structured payment schedule designed to make compliance straightforward for both individuals and businesses.

Payment schedule
The IRD demand note specifies the total tax payable, instalment amounts, due dates, and payment instructions.
Provisional tax is commonly paid in two installments. For Provisional Salaries Tax:
- The first instalment includes any outstanding final Salaries Tax plus 75% of the provisional tax.
- The second instalment covers the remaining 25%.
Exact payment dates vary, so taxpayers should follow the dates printed on their demand note.
Payment methods
Hong Kong’s tax payment system is efficient and flexible. Taxpayers can settle their provisional tax through several channels, including:
- Online banking, Faster Payment System, or other approved electronic channels
- Cheque payment sent by post or made in person at a designated post office
- Payment through banks or ATMs, available at most local institutions
- Phone Payment Service (PPS), allowing payment by phone or the PPS website
All payments should reference the Shroff Account Number printed on the demand note or payment voucher.
Late payment penalties
Failure to pay provisional tax on time may result in additional charges. First, the IRD imposes a 5 percent surcharge on the unpaid balance after the due date. If the tax and initial surcharge remain unpaid six months after the due date, a further 10 percent surcharge may apply to the total outstanding amount.
Continued non-payment could also trigger recovery actions, including garnishee orders against banks, employers, or other parties holding money for the taxpayer(2).
Holdover of provisional tax explained
What is the holdover of Hong Kong provisional tax? This mechanism allows taxpayers to request a reduction or deferral of their provisional tax when their income or profits are likely to decrease. Governed by the Inland Revenue Ordinance, it prevents overpayment and supports more accurate tax settlements.
As the holdover process is not automatic, taxpayers must apply to the Inland Revenue Department (IRD) before the payment due date.
Who can apply
A taxpayer may apply for a full or partial holdover where an applicable statutory ground exists, such as:
- Estimated income, profits, or assessable value falling below the relevant 90% threshold
- A carried-forward loss being omitted or incorrectly stated
- A new allowance or qualifying deduction not reflected in the assessment
- Cessation of a business, taxable employment income, or property ownership
- An applicable Personal Assessment election or objection to the preceding assessment
The available grounds depend on whether the application concerns Salaries Tax, Profits Tax, or Property Tax.
Key differences between the tax holdover and tax incentives
Tax holdover and tax relief or reduction serve different objectives within Hong Kong’s tax framework. In particular, tax holdover allows deferment or suspension of a provisional tax payment when projected income falls. It does not reduce the final tax liability.
Rather, the holdover adjusts payment timing to reflect changed circumstances. Meanwhile, tax relief or tax reduction lowers the total tax payable by granting allowances, deductions or credits, directly reducing the final assessed tax liability.
Key distinctions between the two:
- Purpose: Holdover focuses on matching payment timing to income changes, while relief/reduction aims to lower the amount of tax owed.
- Impact on tax amount: Holdover does not alter the amount owed. Relief or reduction decreases the amount payable.
- Timing benefit: Holdover fuels cash flow by delaying payments. The relief provides a permanent reduction in final liability.
- For example: an employee whose income drops can apply for a holdover, whereas a taxpayer claiming MPF deductions or personal allowances benefits from tax relief.
Knowing how each measure works will let taxpayers manage provisional tax in Hong Kong more effectively and plan finances with greater accuracy. Keep in mind to evaluate whether your circumstances justify a holdover application or qualify for relief or reduction.
Grounds and conditions for applying holdover
Applying for a holdover of provisional tax in Hong Kong requires valid reasons and compliance with specific IRD conditions.
Valid grounds accepted by the IRD
The Inland Revenue Department (IRD) recognizes several valid reasons for applying for a holdover of provisional tax. The most common is when income or profits for the current year are expected to be significantly lower than the previous year’s assessment. The situation often arises from reduced business activity, lower sales, or changes in employment income.
A taxpayer may also apply where a new allowance or qualifying deduction was not reflected in the assessment, a carried-forward loss was omitted or incorrectly stated, or the relevant business, taxable income, or property ownership has ceased. An applicable Personal Assessment election or objection to the preceding assessment may also qualify.
Conditions to note when applying
A holdover application must be submitted no later than 28 days before the payment due date or 14 days after the issue date of the provisional tax notice, whichever is later. The application should include calculations and supporting documents relevant to the claimed ground(3).
Approval is not automatic. The IRD assesses each case carefully and may approve a full or partial holdover depending on the evidence. Until approval is granted, the taxpayer must continue to pay any portion of provisional tax shown as payable.
Application process for holdover of provisional tax
Once a taxpayer confirms eligibility to apply for a holdover, the next step is completing the official application through the Inland Revenue Department (IRD).
How to submit an application
The IRD provides Form IR1121 – Application for Holdover of Provisional Tax for Salaries Tax, Profits Tax, and Property Tax applications.
Eligible taxpayers may apply online through:
- The Individual Tax Portal (ITP) for employment income, property income, and sole-proprietorship profits
- The Business Tax Portal (BTP) or Tax Representative Portal (TRP) for Provisional Profits Tax applications by corporations and other businesses
Alternatively, taxpayers may download Form IR1121, complete and sign the relevant sections, and submit it to the IRD by post or fax. Supporting calculations and documents should be included where required.
What happens after applying
After submission, the IRD reviews the information provided and may:
- Approve the holdover fully or partially
- Request further clarification or documents
- Reject the application if it does not meet the required standards
Taxpayers are advised to monitor their eTAX account or postal correspondence for updates. Unless notified otherwise, the provisional tax shown on the demand note must still be paid on time. If the holdover is approved, the IRD will issue a revised assessment reflecting the reduced amount. When the final tax assessment is completed, any overpayment will either be refunded or credited toward future tax liabilities.
Avoiding costly mistakes with Hong Kong provisional tax
Applying for a holdover provisional tax in Hong Kong can save unnecessary payments, but small mistakes lead to rejection or penalties.
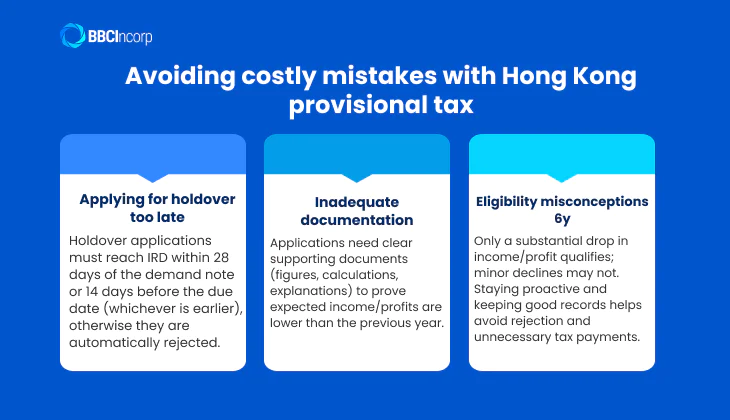
Applying for holdover too late
Timing is important when applying for a holdover of provisional tax. Applications must reach the Inland Revenue Department no later than 28 days before the payment due date or 14 days after the issue date of the provisional tax notice, whichever is later(4).
Late submissions are automatically refused, even if the taxpayer has a valid reason. Thus, setting calendar reminders or preparing documents early helps you stay compliant.
Inadequate documentation
The IRD requires clear and credible proof to justify the application, and submissions without detailed backup are rarely approved. Hence, taxpayers should attach necessary figures, calculations, and written explanations to demonstrate how the expected income or profits differ from the prior year.
Eligibility misconceptions
Not every decline in earnings qualifies for a holdover. The IRD assesses if the income or profit is “substantially less,” based on measurable data. For instance, minor drops in commission or temporary slowdowns may not meet the threshold. Applicants should evaluate their financial situation carefully and consult professionals like BBCIncorp if you are uncertain about eligibility.
Staying proactive, maintaining clear records, and keeping track with the IRD’s assessment criteria reduce the risk of rejection. Businesses that manage their applications correctly avoid unnecessary tax burdens and keep cash flow stable throughout the year.
Streamline your tax obligations with BBCIncorp’s expert support
Handling tax matters in Hong Kong requires accuracy, local knowledge, and consistent compliance. At BBCIncorp, our accounting and tax professionals assist global businesses of all sizes in managing every step of their financial management process.
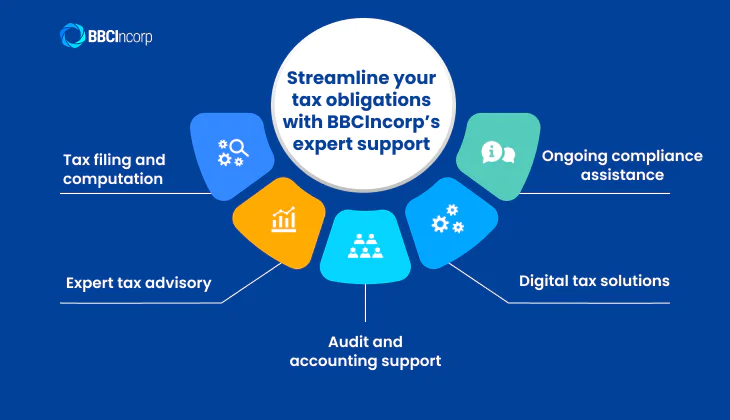
Our Hong Kong tax and accounting services include:
- Tax filing and computation: We prepare and file accurate tax returns for profits and salaries tax, in line with IRD regulations.
- Expert tax advisory: Our professionals analyze your financial position to identify deductions, reliefs, and strategies to optimize tax efficiency.
- Audit and accounting support: We assist with statutory audit coordination and maintain clear, compliant accounting records.
- Digital tax solutions: Our online client portal platform simplifies bookkeeping and reporting, reducing manual errors and ensuring timely submissions.
- Ongoing compliance assistance: We keep clients updated on deadlines, IRD notices, and policy changes to prevent missed filings or penalties.
Whether you run a startup, SME, or international company, our local expertise provides full compliance and reliable support throughout the fiscal year. Visit our website or chat with our team today for timely assistance.
Conclusion
Under the provisional tax Hong Kong framework, taxpayers make advance payments of income tax, supporting consistent revenue collection while enabling easier annual cash-flow management. A thorough understanding of provisional tax calculation, payment schedule, and the holdover mechanism helps prevent overpayments or unnecessary penalties.
BBCIncorp is ready to help with provisional tax filings, holdover applications, and ongoing compliance, contact us for professional guidance to streamline Hong Kong tax obligations efficiently.
References:
- (1): GovHK – Tax Rates of Salaries Tax & Personal Assessment: https://www.gov.hk/en/residents/taxes/taxfiling/taxrates/salariesrates.htm
- (2): IRD – FAQs Instalments: https://www.ird.gov.hk/eng/faq/ins.htm
- (3), (4): GovHK – Holding Over of Provisional Tax: https://www.gov.hk/en/residents/taxes/taxfiling/object/provisional.htm
Frequently Asked Questions
Can I apply to hold over only the second installment?
Yes. If the first instalment has been paid on time, you may apply to hold over all or part of the second instalment, provided you meet an accepted ground and submit the application within the prescribed deadline.
What should I do if my tax assessment is incorrect?
You may lodge a written objection with the IRD within one month after the assessment notice was issued. Clearly state the grounds and provide any required return or supporting documents. You must still pay the amount shown on the demand note unless the IRD advises otherwise.
Can I request additional installments due to financial difficulties?
Yes. You may apply to the IRD for an instalment arrangement and provide evidence of your financial position and a payment proposal. Approval is not automatic, and late-payment surcharges may still apply.
Disclaimer: While BBCIncorp strives to make the information on this website as timely and accurate as possible, the information itself is for reference purposes only. You should not substitute the information provided in this article for competent legal advice. Feel free to contact BBCIncorp’s customer services for advice on your specific cases.
Industry News & Insights
Get helpful tips and info from our newsletter!
Stay in the know and be empowered with our strategic how-tos, resources, and guidelines.


