 Hong Kong incorporation fee & Aspire
 cashback.


Table of Contents
A Certificate of Residence in Singapore is a letter issued by the Inland Revenue Authority of Singapore (IRAS) confirming that a company is a Singapore tax resident for a specific calendar year. Companies use it to claim reduced withholding tax and other benefits under Singapore’s Double Taxation Agreements (DTAs).
Applying for a COR may initially appear complex, but with our comprehensive guidelines, you can easily navigate the process and position your company for success. Let’s begin.
Key Takeaways
- A COR is issued by IRAS to certify Singapore tax residency for a specific calendar year, based on where control and management of the business is exercised.
- Nominee companies, non-Singapore incorporated companies, and Singapore branches of foreign companies are generally not eligible for a COR.
- Foreign-owned investment holding companies with only passive or foreign-sourced income must additionally show a Singapore based executive director, key employee, or a managing related company in Singapore.
- Online COR applications are processed within 7 working days; written applications for special cases take up to 14 working days.
- Companies can apply for the current calendar year, up to 4 back years, and 1 advance year starting from October.
What is the Singapore Certificate of Residence (COR)?
The Certificate of Residence (COR) is issued by the Inland Revenue Authority of Singapore (IRAS) to certify that a company is a tax resident in Singapore.
Why is this document important to your company? First, it serves as a concrete testament to your business status in this jurisdiction.
Moreover, this esteemed certificate grants you access to benefits under the Avoidance of Double Tax Agreements (DTAs). These benefits usually include:
- Double taxation relief thanks to foreign tax credits;
- Tax exemptions and reductions for certain types of income or transactions; and
- Other benefits of cross-border economic transactions (e.g. provisions related to the taxation of business profits, pensions, social security contributions, etc.)
DTA benefits are exclusively for Singapore tax residents and DTA partners. To utilize these benefits, you must provide your COR as proof of Singapore tax residency to foreign tax authorities. Obtaining a COR is essential to protect your DTA rights.
Imagine this scenario: Your company, based in Singapore, provides consulting services to a firm based in a country that has established a tax treaty with Singapore. Under normal circumstances, revenue earned from these consultancy services could be subject to a 15% withholding tax in the client’s jurisdiction.
However, with a Certificate of Residency from Singapore, your company can take advantage of the provisions outlined in the Double Taxation Agreements (DTAs).
By presenting the COR, your company may be eligible for a reduced withholding tax rate, potentially as low as 10%. This can lead to significant cost savings over time, reinforcing the value of obtaining a COR for businesses operating in Singapore.
Indeed, this certificate holds immense value for multinational corporations establishing a strong presence in Singapore, but specific conditions must be fulfilled
This leads us to the question: What are the crucial eligibility criteria for the COR application? Let’s find out.
What are the eligibility criteria for the COR application?
To apply for COR, your company must qualify as a tax resident of Singapore. The sections below explain exactly how that residency status is determined, and what causes a company to fall short of it.
How to qualify as a Singapore tax resident?
Tax residency in Singapore is determined by the location of key operational activities and strategic decisions rather than by the place of incorporation.
In general, a company is regarded as a Singapore tax resident for a specific Year of Assessment (YA) if the control and management of its business operations were conducted in Singapore during the preceding calendar year.

Note
Assuming that your company’s control and management were solely conducted in Singapore throughout 20252, consequently, your business is considered a Singapore tax resident for the YA 2026.
In practice, IRAS looks at a specific set of facts to determine where that control and management genuinely sits. The two checklists below break this down into what typically counts as control and management in Singapore, and what typically doesn’t.
When is control and management considered exercised in Singapore?
IRAS generally treats control and management as exercised in Singapore when the following apply:
- Board of Directors’ meetings are held in Singapore;
- Strategic decisions are made at those Board meetings held in Singapore;
- The directors who make strategic decisions are based in Singapore;
- The local director actively makes strategic decisions, not just routine ones;
- Key employees (e.g. CEO, CFO, COO) are based in Singapore.
Which companies may not be eligible for COR?
Following the aforementioned criteria, there are cases where certain types of companies may, unfortunately, be ineligible for the Certificate of Residence (COR). Let’s explore a few common situations.
Non-Singapore incorporated companies
Companies in this category are typically not controlled or managed in Singapore, therefore ineligible for a COR. This also applies to branches of foreign companies, as they are under their overseas parent companies’ surveillance.
However, IRAS may still issue a COR if a non-Singapore company can demonstrate that:
- The company exercises control and management of its business in Singapore; and
- There are valid reasons not to incorporate in Singapore.
For companies that fall within this category, IRAS may request further information for clarification purposes.
Foreign-owned investment holding companies
An investment holding company whose income is solely passive and received from foreign sources is not eligible for COR application.
A business is regarded as a foreign-owned investment holding company if
(1) It has 50% or more of its shares held by:
- Foreign companies incorporated outside Singapore; or
- Individual shareholders (who are not Singapore citizens); and
(2) Its ownership is applied at the ultimate holding company level.
Fortunately, IRAS may still treat such a company as a Singapore tax resident if two conditions are met:
- Control and management of the business is exercised in Singapore — demonstrated in part by holding Board of Directors meetings in Singapore; and
- The company can show a genuine commercial reason for being based in Singapore, by satisfying at least one of the following:
- Having at least one director based in Singapore who holds an executive position and is not a nominee director;
- Having at least one key employee (e.g. CEO, CFO, COO) based in Singapore; or
- Being managed by a related company based in Singapore — for example, that related company makes decisions on the holding company’s operations or reviews its investment performance.
- Meeting both conditions may make a company eligible to apply for a COR, despite the business being foreign-owned.
Meeting all of these criteria may make a company eligible to apply for a COR, despite the business being foreign-owned.
Nominee Companies
In the legal sense, a nominee company serves as a holder of shares on behalf of its beneficial owners. Since nominee companies are not the beneficial owner of the income derived from the DTA partner, they cannot obtain a COR.
The COR is typically granted to the actual beneficial owners of the income, who are entitled to the economic benefits and bear the risks associated with the income generated.
How to get certificate of residence in Singapore
To streamline the procedures, you must submit the COR application electronically through the IRAS myTax Portal, unless specified otherwise for certain circumstances. You can visit the myTax portal here.
Below is the step-to-step outline of the process:
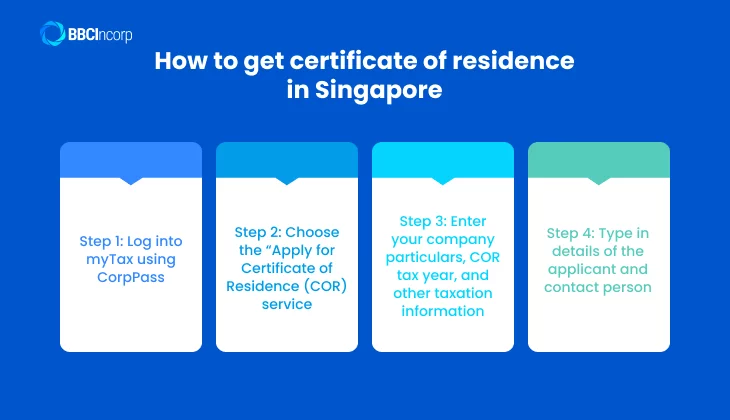
Step 1: Log into myTax using CorpPass
The first step is to visit the myTax Portal and log in to the system using your company’s Singapore CorpPass credentials.
Once logged in, you should be able to locate the menu area. Click on e-Service and select Corporate Tax.
Step 2: Choose the “Apply for Certificate of Residence (COR) service
Within the Corporate Tax section, choose the option Apply for Certificate of Residence (COR) to proceed with the application.
A new window or page will appear with the COR application form. Click on Proceed to access the document.
Step 3: Enter your company particulars, COR tax year, and other taxation information
After accessing the form, you shall enter the company particular details (e.g. the business name, type, registered address, key officers, etc.), the treaty country (if applicable), and the tax year for the COR.
Per the needs and nature of your business, you can apply for a COR for the following years:
- The current calendar year
- No more than 4 back calendar years
- 1 advance calendar year, commencing from October of the current calendar year.
For instance, in November of the calendar year 2025, your business can apply for a COR covering 2021 to 2026.
Once the filing is completed, move on to the confirmation page. At this stage, you have the option to save the page as a PDF file or print it to keep hard copies.
Step 4: Type in details of the applicant and contact person
In this step, you will be required to provide information about the applicant and contact person. This might encompass your name, designation, phone number, and email address.
In addition, you must agree to the terms and conditions stated. Once the information is verified, you can submit the application.
Upon submission, you will receive a confirmation indicating that your COR application has been successfully received. You should actively monitor the application status and stay attentive to any updates from the tax authority for the best results.
What happens after you complete the process?
The IRAS normally takes 7 working days to go through your application from the date of receiving the application.
After the application is processed successfully, IRAS will send you a notification via email or physical mail to the company’s registered address.
If your company opts for email notifications as its notice preference in the Update Notice Preferences service, an email will arrive within 1-3 working days. The email shall state that the digital COR is available on myTax Portal. In this case, no physical COR is sent.
However, if you select paper notices, please expect to receive the paper COR at the registered address within 4 working days.
Please note that the timelines and procedures for notifying the results may vary depending on the specific circumstances.
Upon approval, you will have access to a digital copy of the COR through the myTax Portal’s View Notices/Letters – Corporate Tax digital service. You can also print or download the COR for record-keeping.
Conclusion
Overall, the Certificate of Residence plays a vital role in facilitating tax benefits for businesses in Singapore. It enables enterprises to benefit from tax exemptions such as Double Taxation Agreements and other treaties.
While certain requirements must be met, the process has been made more convenient through the myTax Portal. Simply follow our guide to submit your certificate of residence in Singapore application with ease!
If you have further questions about doing business in Singapore, chat with us. Our team is ready to provide timely support.
Frequently Asked Questions
Can your tax agent apply for the COR on behalf of your company?
Yes, your tax agent can apply for the COR on behalf of your company. However, you will need to authorize your tax agent as an “Approver” to do so.
In that case, please refer to the COR application guide for tax agents provided by the IRAS for clearer instructions.
How can an individual apply for a Certificate of Residency in Singapore?
To apply as an individual, you must complete and submit the specific IRAS form for your residency status: one form for Singapore Citizens or Permanent Residents, a different form for self-employed individuals, sole proprietors, or partners in a partnership, and another for foreign employees who hold a FIN and SingPass.
You can find the appropriate forms on FormSG’s website, and you must submit a separate application for each Year of Assessment.
When does your company have to apply for a COR in writing?
You must submit a written COR application if your company is applying for a COR on behalf of a sole-proprietorship business it owns, if your company is applying as a partner in a partnership business, or if your company is a non-Singapore incorporated company.
Due to the complexity of the required documents, IRAS typically takes up to 14 working days to process a written application, and once approved, you can access the certificate via myTax Portal.
Can a Variable Capital Company (VCC) apply for the COR?
A Variable Capital Company can apply for the COR. Note that the VCC itself, rather than its individual sub-funds, must be a Singapore tax resident to apply for its COR.
In this case, the certificate will then show both the details (tax reference number and name) of the VCC and its sub-funds (if any).
Is there a deadline for submitting a COR application?
Yes. If you intend to claim treaty benefits, you should submit your COR application before claiming those benefits, and at the latest within 2 calendar years from the actual or expected date of receipt of the foreign income. Applying after this window may put your ability to claim DTA relief at risk, so it’s best to apply as soon as the relevant income is confirmed.
Disclaimer: While BBCIncorp strives to make the information on this website as timely and accurate as possible, the information itself is for reference purposes only. You should not substitute the information provided in this article for competent legal advice. Feel free to contact BBCIncorp’s customer services for advice on your specific cases.
Industry News & Insights
Get helpful tips and info from our newsletter!
Stay in the know and be empowered with our strategic how-tos, resources, and guidelines.


